SpaceX seeks financing for a reported $40 billion Nvidia GPU purchase, exposing the scale and leverage of AI infrastructure
SpaceX is in preliminary talks with Apollo Capital Management and a group of banks to fund a potential $40 billion acquisition of Nvidia graphics processors, a deal that would rely heavily on investment‑grade debt and highlight how AI hardware expansion is increasingly tied to capital markets.
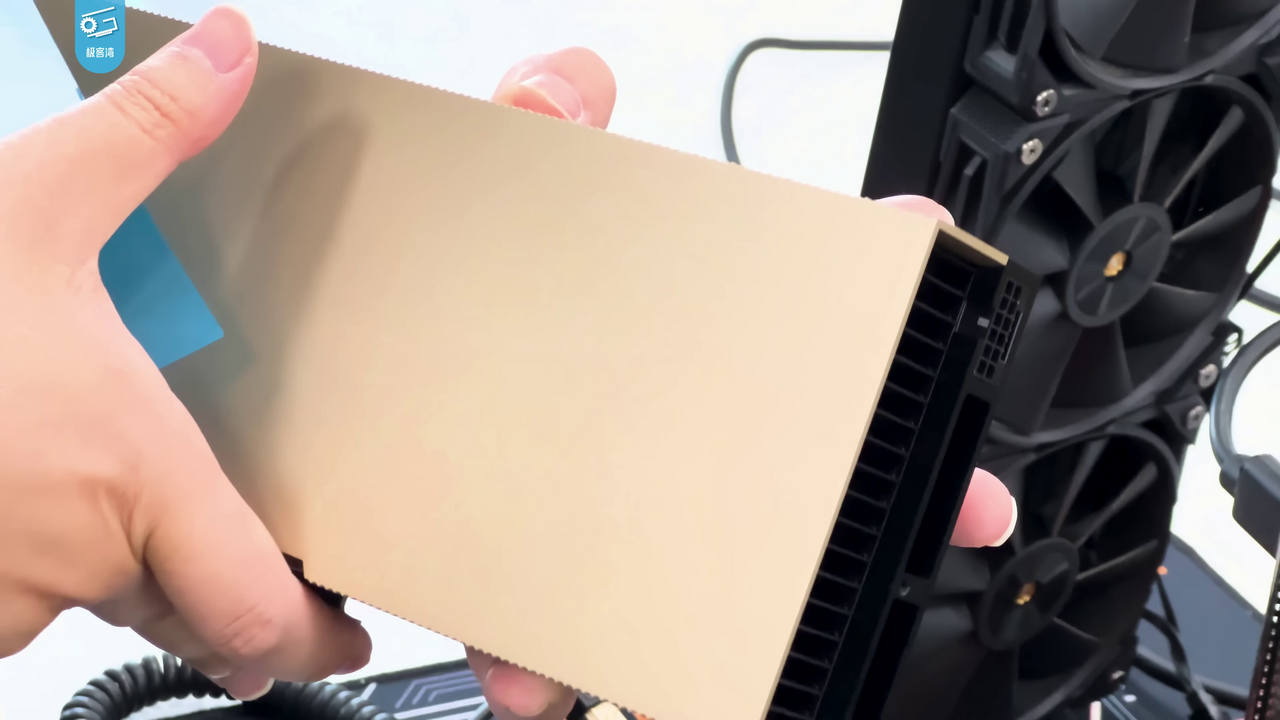
SpaceX eyes $40 billion Nvidia GPU purchase
On 7 October 2026, CNBC reported that SpaceX was in early discussions with Apollo Capital Management and several banks to finance a reported $40 billion purchase of Nvidia graphics processing units (GPUs). The information was attributed to a source familiar with the talks who asked to remain anonymous. At the time of reporting, the identities of the lenders and the exact financing structure had not been finalised, and both Apollo and Nvidia declined to comment. The Financial Times was cited as the first outlet to flag the financing discussions.
Proposed financing structure
According to CNBC, the tentative financing plan would lean heavily on investment‑grade debt, with the GPUs themselves potentially serving as collateral. A credit‑market source told CNBC that lenders are assuming high‑end GPUs can retain value for roughly seven years, a market‑based assumption rather than a guarantee. Techzine, reporting independently on the same day, described a possible split of about $10 billion in bank loans and $30 billion in investment‑grade bonds, with Apollo playing a leading role and Pimco reviewing the transaction.
- $10 billion bank loans
- $30 billion investment‑grade bonds
- GPU collateral valued for ~7 years
Debt market backdrop and SpaceX’s existing liabilities
SpaceX raised $25 billion in bonds after its June 2026 initial public offering, and demand for those bonds was described as strong. However, CNBC noted that AI‑related bonds have since sold off and credit spreads have widened, prompting investors to become more selective. In its second‑quarter financial statements, SpaceX reported nearly $40 billion in debt, with its existing notes trading near junk‑bond levels. The contrast between the strong IPO bond demand and the current market softness underscores the challenge of securing large‑scale, investment‑grade financing for AI hardware.
Assumptions about GPU collateral value
The financing model hinges on the belief that Nvidia’s high‑performance GPUs will hold sufficient resale or lease value to back the debt. The credit‑market source cited by CNBC said lenders are assuming a seven‑year value retention horizon, but stressed that this is a market assumption, not a contractual guarantee. Should GPU prices fall faster than expected, or if resale markets weaken, the collateral value could erode, potentially forcing lenders to renegotiate terms or demand additional security.
Scale of SpaceX’s AI hardware deployment
Elon Musk, in a 24 September post referenced by CNBC, said SpaceX’s AI supercomputers—codenamed Colossus and Colossus 2—were operating 230,000 and 550,000 Nvidia chips respectively. Musk added that the company aims to reach 1.21 million chips by late December if market conditions allow. Those figures illustrate the massive compute appetite driving the proposed $40 billion spend and highlight why SpaceX is looking to lock in financing now, before any further market tightening.
Early‑stage nature and timeline
Both CNBC and Techzine stress that the financing discussions are at an early stage and no definitive agreement has been signed. Techzine reported that the transaction could be completed in 2027, pending finalisation of loan and bond terms and confirmation from SpaceX, Nvidia and Apollo. The reports also note that while Apollo is positioned as a lead arranger, other banks and institutional investors are expected to participate, and that the final mix of debt instruments could shift as market conditions evolve.
Implications for AI infrastructure financing
If the proposed financing proceeds, it would be a landmark example of AI infrastructure expansion being underpinned by large‑scale debt markets rather than solely by corporate cash reserves. The reliance on investment‑grade bonds and bank loans signals that even well‑capitalised tech firms may need to tap broader capital markets to fund the compute power required for next‑generation AI models. It also puts pressure on lenders to develop new risk‑assessment frameworks for hardware‑backed collateral, a niche that could become more common as AI workloads proliferate.
Uncertainties and next steps
At present, the financing arrangement remains a proposal, with key terms, participants and timing still uncertain. What changes now is the heightened visibility of how AI hardware spend is being linked to debt markets, prompting investors to scrutinise the durability of GPU collateral and the credit quality of borrowers like SpaceX. As the market watches, any shift in Nvidia’s pricing, credit‑spread movements, or SpaceX’s own financial health could reshape the final structure—or even halt the deal altogether.
Sources
- SpaceX in talks with Apollo, banks to back $40B Nvidia chip buyCNBC · October 7, 2026
- SpaceX wants to borrow $40 billion for Nvidia chipsTechzine Global · October 7, 2026